
It’s 14 years since LADbible was launched in the UK’s northwest by schoolfriends Alexander “Solly” Solomou and Arian Kalantari. Solomou (now CEO) had developed the idea while studying business at university. It started with a Facebook posting that snagged over 75k readers. That was just the start of a what has become an enduringly successful digital publisher. It is impossible not to connect LADbible with the “lads” magazines – FHM, Loaded, Maxim, Nuts and Zoo – which had sold millions of copies and stamped British “blokeyness” across the world in the last decade of the 20th century.
But there is now little similarity between those meteoric, relatively short-lived (but hugely profitable) magazines and LADbible whose LBG Media parent has a total global audience of 520mn – some 45% of whom are women. Yes.
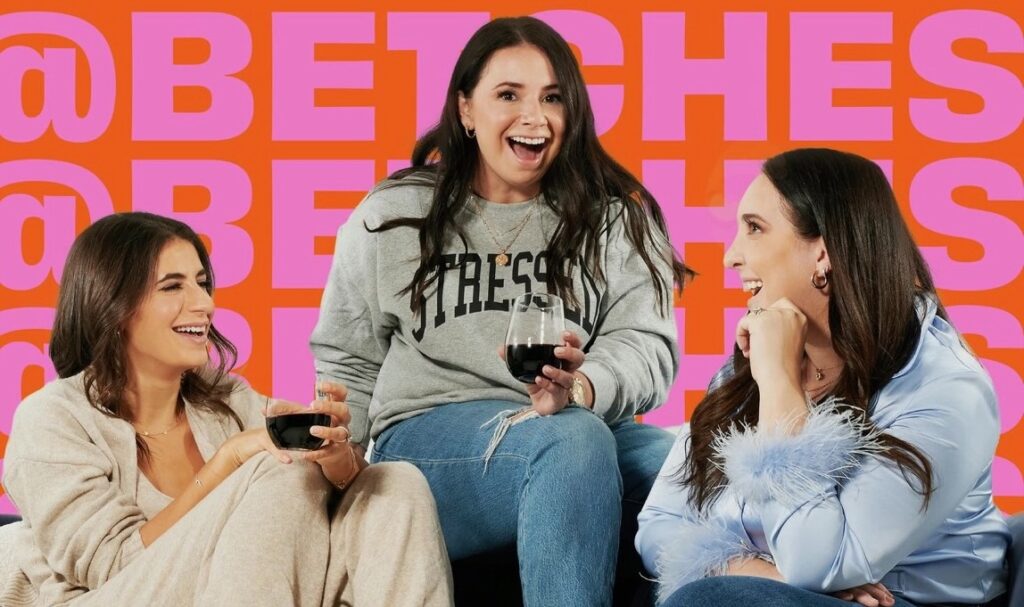
It’s a long way from the early days of LADbible male banter and sexist jokes and, as if to emphasise the changed times, LBG’s $30mn acquisition in 2023 of the US site Betches for women and girls, may soon account for at least 25% of the group’s revenue. With Betches now set to launch in the UK (starting notably by targeting those UK women who are already in the LBG audience) it may not be too long before the company’s brands really do appeal equally to millennial and Gen Z men and women.
In addition to Betches, LBG brands include SPORTbible, GAMINGbible, UNILAD and Tyla. Its user-generated and publisher content is a lively, high-quality blend reminiscent more of vintage Vice and BuzzFeed than FHM. Comparisons with the egregiously well-funded US high-fliers might, of course rankle with the LBG founders who bootstrapped their listed company and still own some 60% of its shares.
LBG claims to be “the largest youth publisher in the world” with the declared purpose of giving young adults “a voice by building communities that laugh, think and act”. But nobody doubts that the Betches acquisition is pivotal for LBG with Solomou now spending up to half his time in New York where the company is claiming “some really big wins among big brand advertisers”. The deal had followed the successful US acquisition of UNILAD back in 2018 and insiders predict further US investments by LBG. It’s got the cash and bank credit to finance up to £90mn of deals.
But it’s clear that Betches is a big step for LBG Media, both in its determination to build a much bigger US business but also in its launch plans for the UK which – after a soft launch last month – will be intensified “around October”. The vague timing and the assertion that UK staffing will only be stepped-up once revenue starts to flow are interesting. Maybe the company, having trumpeted the launch plans loudly in the spring, is now choosing to manage the expectations of advertisers and investors alike.
LBG chair Dave Wilson told Flashes & Flames this week: “We want to start with a few editorial formats that we know will land with our audience before we grow into different revenue streams, whether that’s podcasts or longer form content on YouTube, and then vice versa with commercial partners. We’re not going out to the full market. We’re being quite targeted with our approach and who we’re bringing on board as launch partners. But I imagine we’ll develop very, very quickly by the end of the year, once we start to introduce our original editorial. But we’re being very targeted with our growth strategy, both commercially and editorially.”
You might think this is a new, cautious, under-stated tone from the company which has built its enviable audience by being brave, bold and exciting. But it’s a similar realism that motivated LBG – after years of claiming high-pentration success in Australia and Ireland – to eschew some millions of pounds of low-margin revenue by sub-contracting those operations and choosing, instead, to concentrate on the US and UK.
The calm seriousness might just fit with the recent financials.
While LBG’s annual results have become confused by the recent depreciation of the US dollar (which accounts for about one-third of revenue) and by the decision to change to an end-September financial year, 2025 is expected to produce strong like-for-like growth for the debt-free company.
| SnapShot LBG Media Plc | |||
| £mn Yr to Sept. | 2025* | 2024 | 2023 |
| Revenue | 92 | 65 | 68 |
| US | 35% | 32% | 14% |
| UK | 35% | 37% | 35% |
| RoW | 30% | 31% | 51% |
| EBITDA | 24 | 17 | 17 |
| Margin | 26% | 26% | 25% |
| People | 485 | 471 | 446 |
| Audience | 520mn | 503mn | 452mn |
| Net cash £mn | 32 | 27 | 16 |
First-half results for the six months to March this year saw LBG achieve £43.9mn revenue (+13%) and £12.2mn EBITDA (+18%), a 28% margin. The company claims 17 of its advertising clients now account for more than $1mn annual revenue – double the number in the previous year and boosted by the US performance. But the weakening dollar is estimated to reduce full-year revenue by £2mn and EBITDA by £1mn.
LBG is predicting significant longterm growth, buoyed by the rapid growth in the digital advertising market and the rising buying power of millennial and Gen Z young people (born during 1997-2012). The digitally native Gen Z is said to account for 17% of global consumer spending.
But buried in the half-year financials is some suspicion that the poor cost control which once plagued the company (which once had 31% EBITDA margins) may not have been entirely extinguished. In the first-half, the combination of content, payroll and overhead costs increased year-on-year by no less than 11%.
That might not be the limit of concerns about LBG whose share price has lost 28% so far this year and whose £180mn enterprise value is 50% of the IPO four years ago. It may not, of course, be helped by the fact that the company has yet to pay any dividends to shareholders.
While there can be no doubt that LBG Media – especially its flagship brands LADbible and, now, Betches – are great media properties with a brilliant, authentic multimedia voice for a captivated audience that will multiply the current 500k if it can become build strongly in the US. In the UK, arguably, nobody talks to this millennial-Gen Z audience better than LBG; matching that in the US would be a huge prize.
But the business model may just be a problem.
LBG self-consciously tells investors about its “increasingly diversified revenue base”. The trouble is that when other media companies use those words, they usually mean some kind of mix of advertisers, readers, events, eCommerce and licensing. In this case, LBG is referring to the roughly 50:50 split between direct advertising and programmatic revenues shared with the platforms. The company has (like so much other media) been trying to reduce this dependance on the voracious platforms. At the time of IPO in 2021, some 37% of its revenue came just from Facebook; now it’s 23%. But LBG’s market strength and the importance of its ‘indirect’ revenue makes programmatic advertising seem a more durable source of revenue than many would suggest.
There’s another elephant in the room.
As to complicate LBG’s revenue puzzle, there is its longterm dependance on a single advertiser which, over the last four years, has accounted for £78.2mn (31% of total revenue).
That unnamed dominant advertiser is believed (but not confirmed) to be Uber Eats whose share of LBG revenue last year was “only” 20% having been as high as 38% in 2021. Incidentally, the following year, two companies had together accounted for no less than 44% of all LBG revenue.
While it is not Uber Eats’ largest UK media outlet (that honour belongs to Sky Sports TV), you can see how vulnerable LBG may be to any kind of cutbacks. LBG has mounted some significant campaigns such as Euro 2024 Snack Wars for Uber Eats and is, presumably, a great partner. But the scale of budgets makes you realise that some direct advertising may not be any more “safe” than the programmatic revenue that everyone worries about.
But, whichever way you look at it, LBG is clearly over-dependant on the platforms and must, surely, search for ways of diversifying revenues, presumably through reader-users, events (something that Betches already does successfully in the US) and even eCommerce – not just switching to direct ads and branded content.
It clearly aims to do at least some of this over time – but is focused right now on stretching to replicate its UK success across the Atlantic. Who can say whether it could or should do it in reverse? Or whether the sheer authenticity of LBG Media, the compelling value of its hard-to-reach audience and unrivalled multimedia smarts make it less vulnerable than our own observations might imply.
Perhaps the obvious strategic compromise would be for the achingly self-confident LBG Media to concentrate its promised wave of M&A on operations that create the scope for real revenue diversification – while also seeking to conquer the US. Let’s watch.